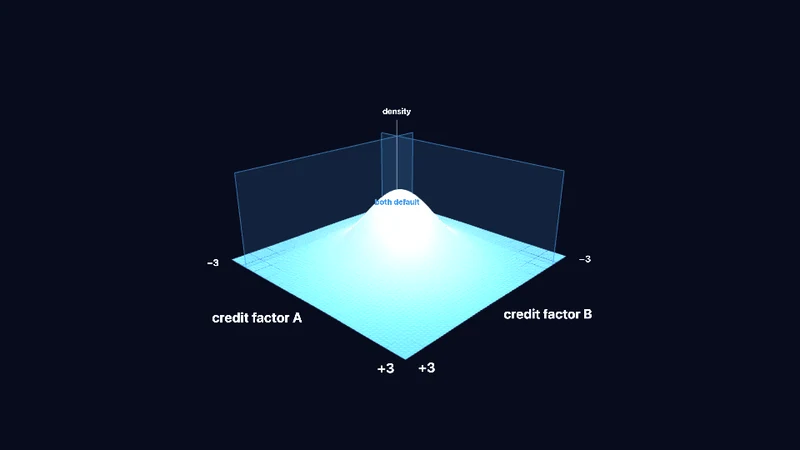
Asset correlation in 3D
Rotate a bivariate normal density, adjust correlation and default thresholds, and see how joint default probabilities change.
Financial Risk & AnalyticsTry itVisuApps
Explore discrimination, PD calibration, asset correlation and risk-bearing capacity through interactive quantitative models.
Apps
Rotate a bivariate normal density, adjust correlation and default thresholds, and see how joint default probabilities change.
Financial Risk & AnalyticsTry it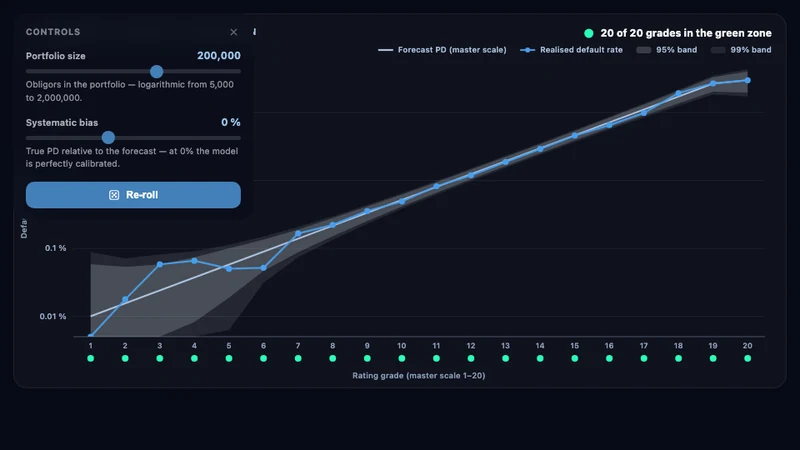
Compare predicted default probabilities with realised rates across twenty rating grades, including confidence bands, portfolio size and systematic bias.
Financial Risk & AnalyticsTry it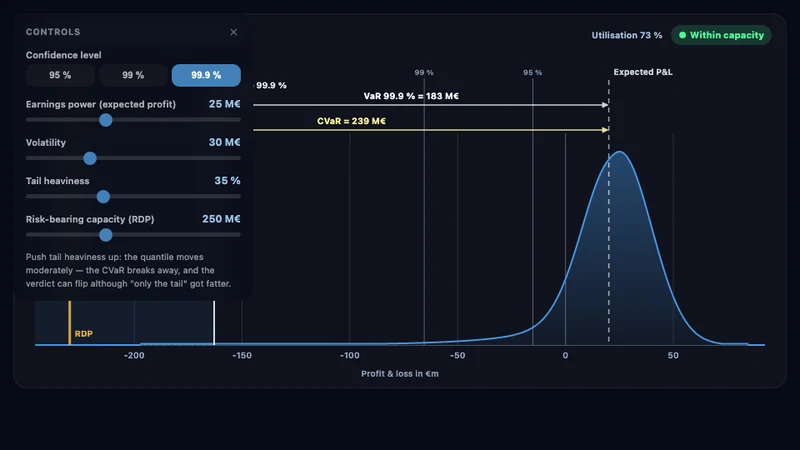
Compare a profit-and-loss distribution, quantiles, expected results, VaR and CVaR with risk coverage. Adjust confidence and tail severity.
Financial Risk & AnalyticsTry it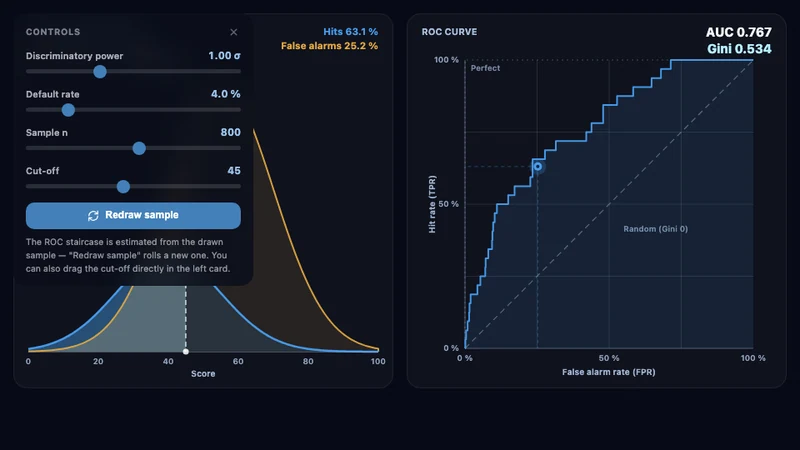
Adjust default and non-default score distributions, sample size and cutoffs. See the ROC curve, AUC and Gini update live.
Financial Risk & AnalyticsTry it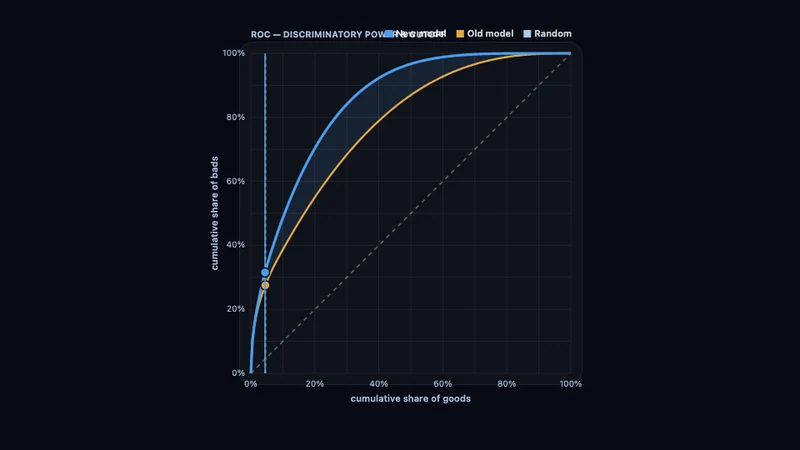
Compare two scoring models at a chosen acceptance rate. Inspect how many additional defaults are caught and good customers retained.
Financial Risk & AnalyticsTry itWant to use these apps in your courses? Let’s find out what works for you.
One form, three matters. We answer personally.
We show heyprof on your own material. Tell us what you teach and we will prepare the conversation around it.