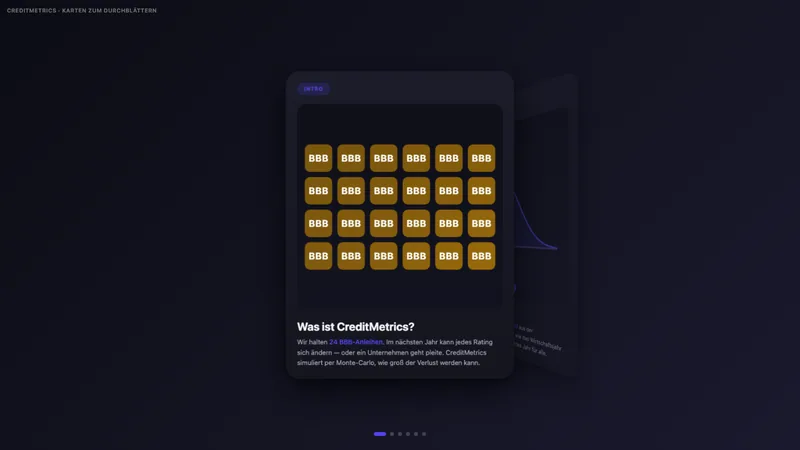
CreditMetrics — credit portfolio model
Monte-Carlo simulation in single steps: systematic factor, correlated returns, rating migration and loss distribution with EL, VaR and Expected Shortfall.
IRBA / banking supervisionTry itVisuApps
Methodological core points of internal rating systems under CRR and EBA guidelines
Apps
Monte-Carlo simulation in single steps: systematic factor, correlated returns, rating migration and loss distribution with EL, VaR and Expected Shortfall.
IRBA / banking supervisionTry it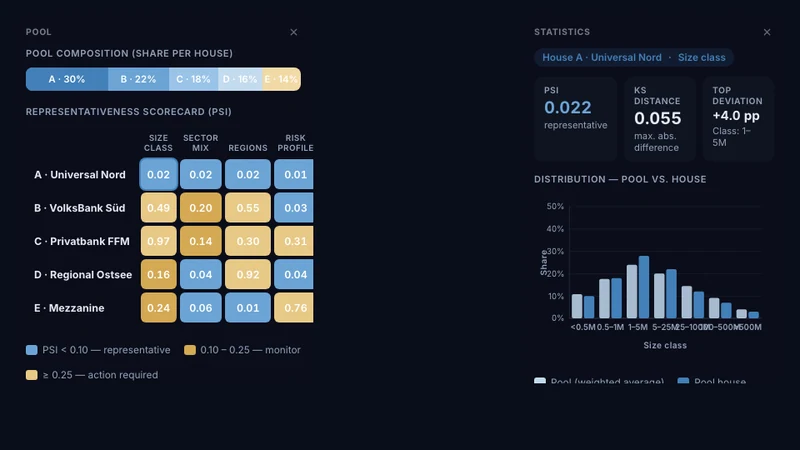
Centrally developed method at pool level, representativeness evidence per pool bank across several dimensions.
IRBA / banking supervisionTry it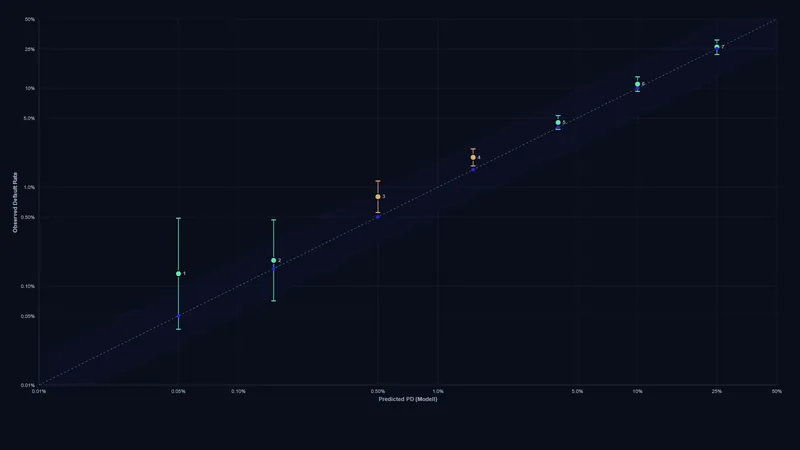
Predicted PD vs. observed default rate, binomial confidence bands and traffic light per rating grade.
IRBA / banking supervisionTry it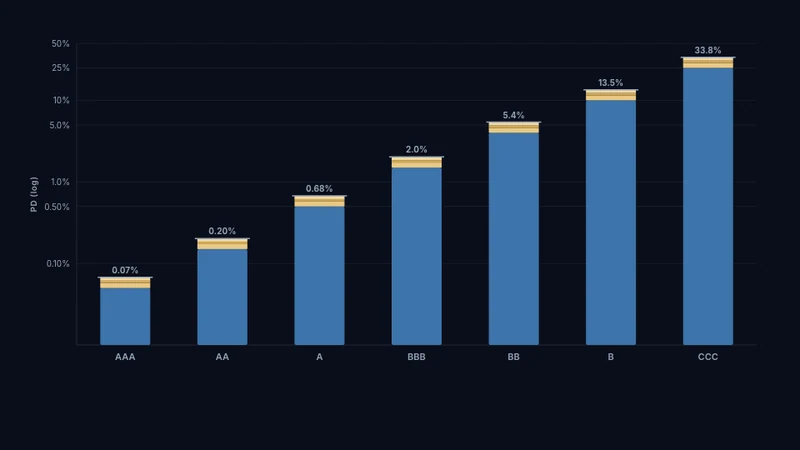
Stack and aggregate the add-ons of categories A, B and C interactively — per rating grade.
IRBA / banking supervisionTry itWant to use these apps in your courses? Let’s find out what works for you.
One form, three matters. We answer personally.
We show heyprof on your own material. Tell us what you teach and we will prepare the conversation around it.