Adverse selection
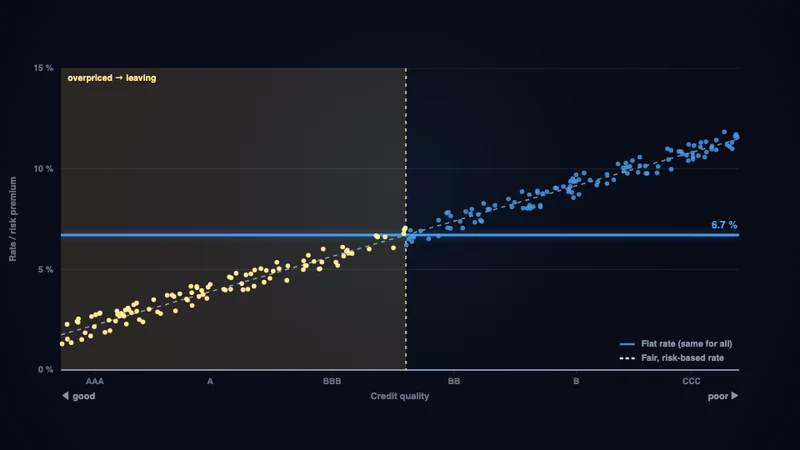
Explore how a uniform lending rate can drive lower-risk borrowers out of a credit market.
Credit riskTry itVisuApps
Counterparty, spread and credit-portfolio risk — interactive: loss distributions, migration, pricing, risk-bearing capacity.
Apps
Explore how a uniform lending rate can drive lower-risk borrowers out of a credit market.
Credit riskTry it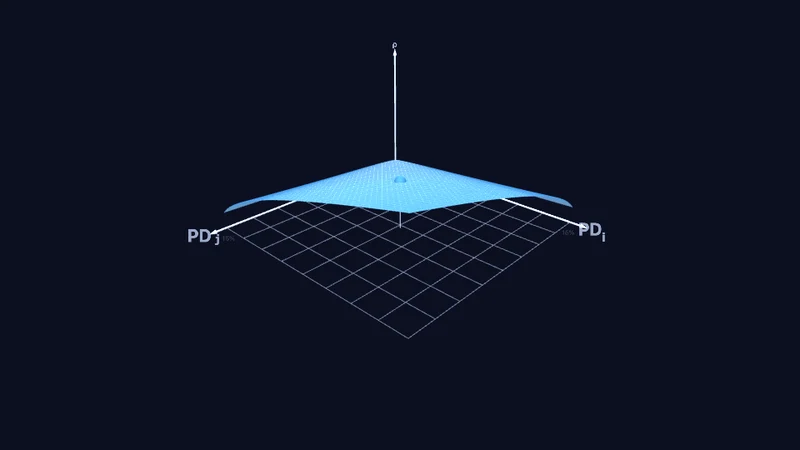
Explore how default correlation depends on probability of default and asset correlation using a 3D surface.
Credit riskTry it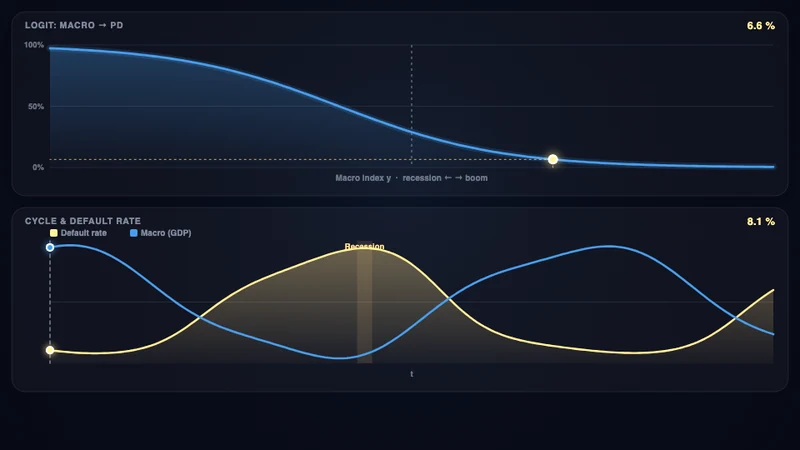
Explore how macroeconomic factors drive default rates over the business cycle in CreditPortfolioView.
Credit riskTry it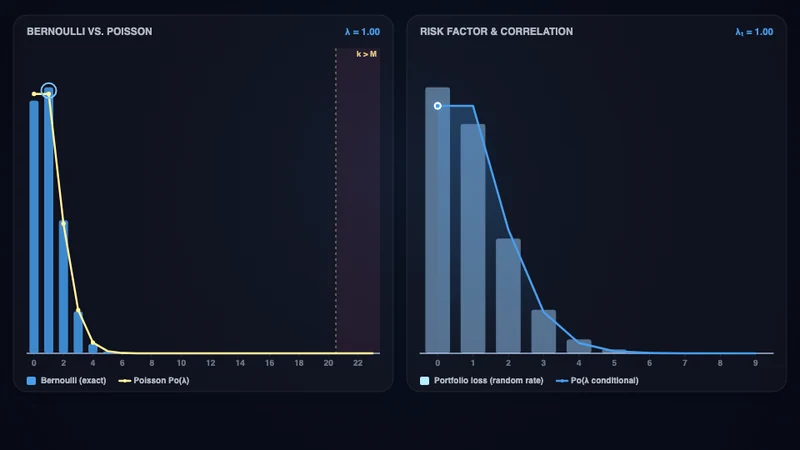
Move from Bernoulli defaults to a Poisson approximation of default counts and an analytical credit loss distribution.
Credit riskTry it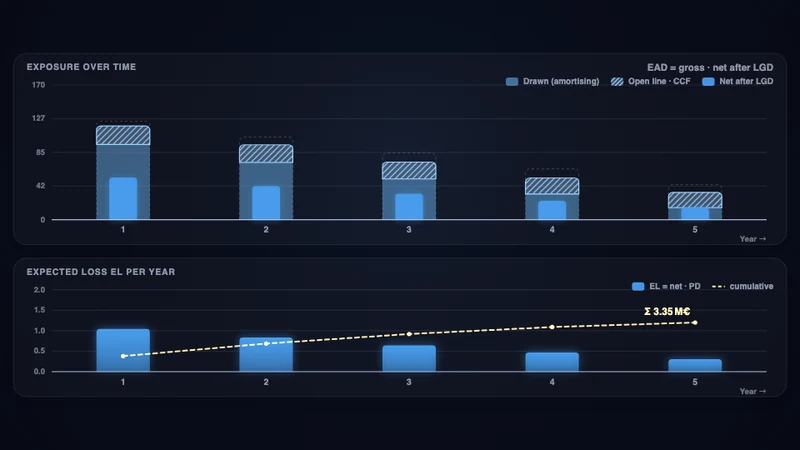
Explore expected and potential future exposure over time, alongside expected loss.
Credit riskTry it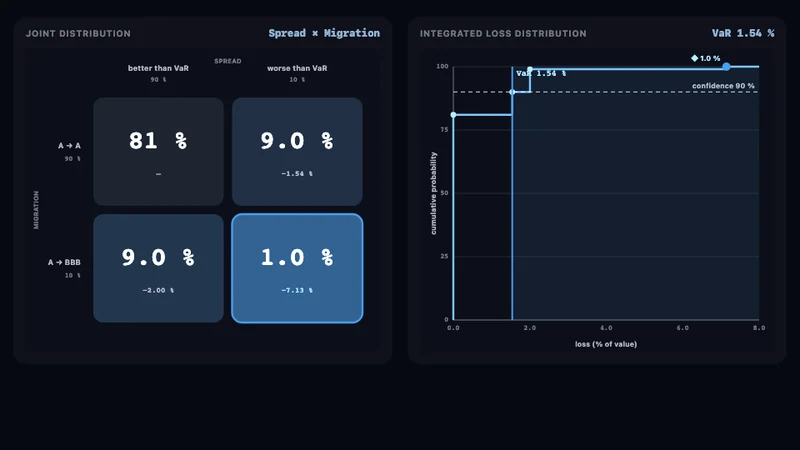
Combine migration risk and spread risk in a single measurement of portfolio losses.
Credit riskTry it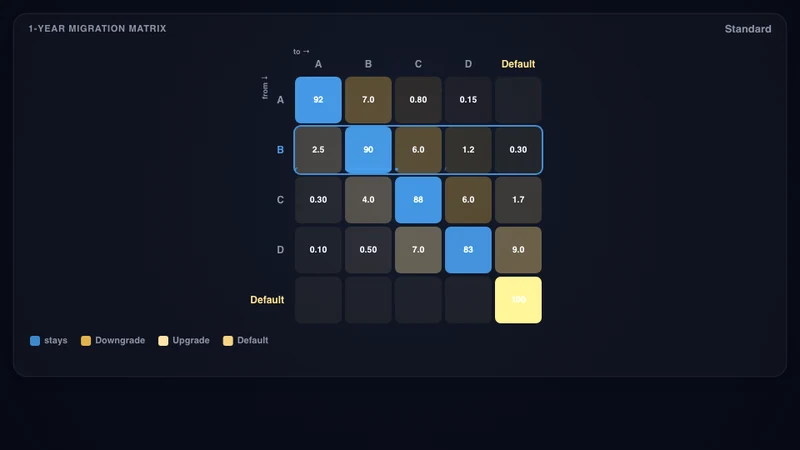
Explore a rating migration matrix, transition probabilities between rating grades and migration over multiple years.
Credit riskTry it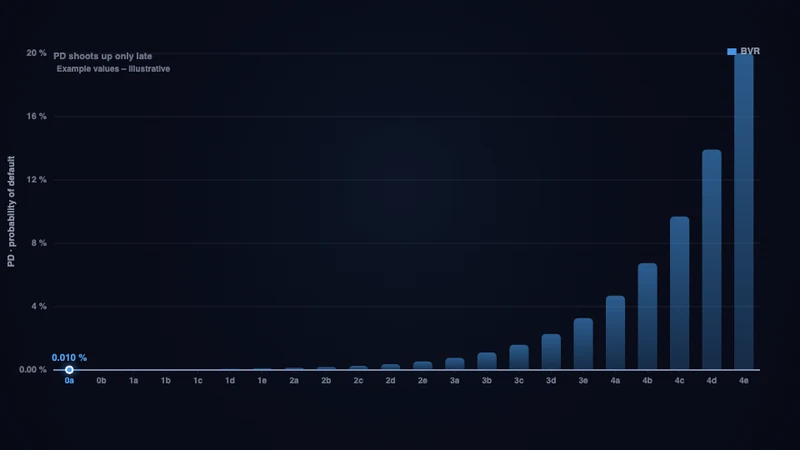
Explore rating grades, their probability-of-default bands and the calibration of a master scale.
Credit riskTry it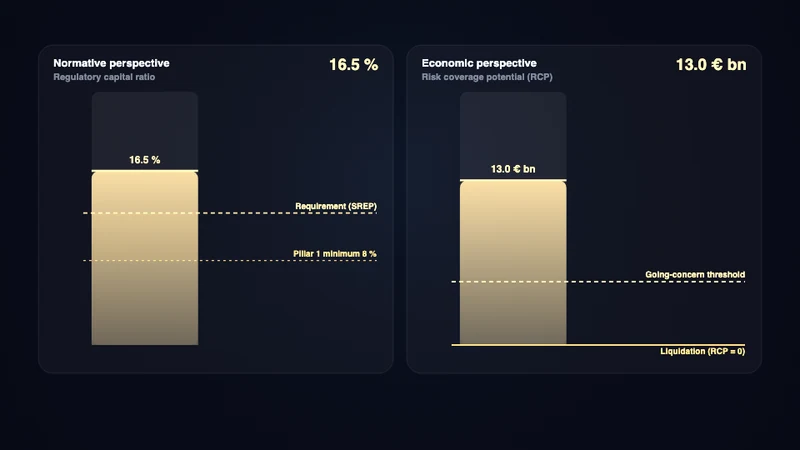
Compare available risk coverage with aggregated risks and monitor capacity utilisation.
Credit riskTry it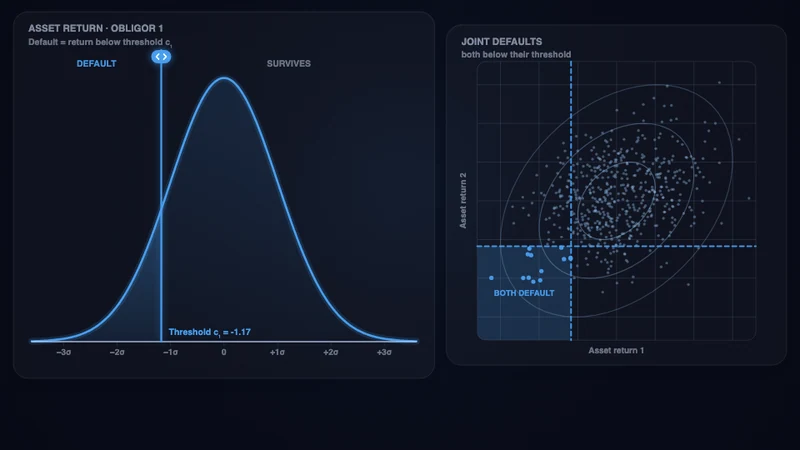
Explore default when firm value falls below a debt threshold and investigate the role of asset correlation.
Credit riskTry it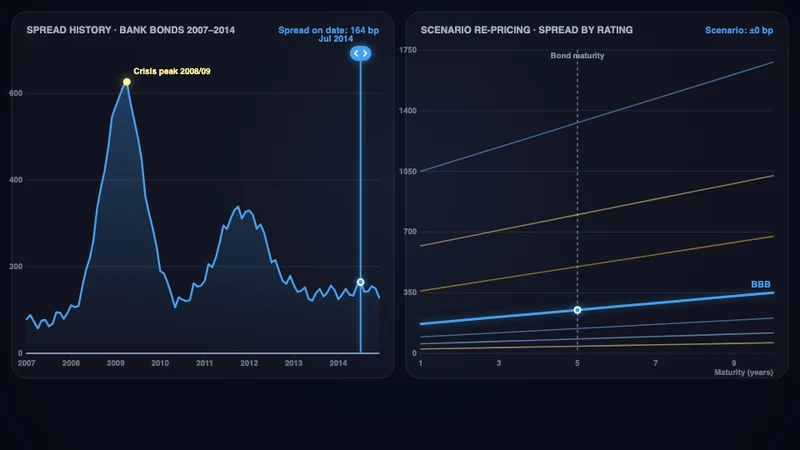
Decompose credit spreads into default, liquidity and risk premiums across maturities.
Credit riskTry it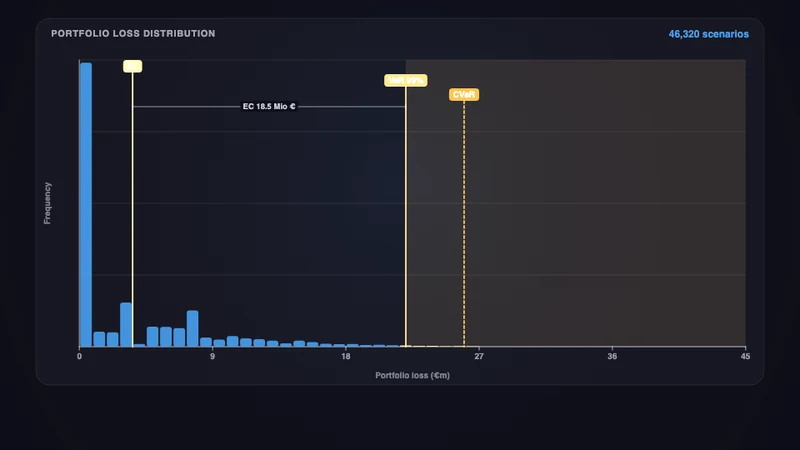
Simulate a credit portfolio’s loss distribution and explore expected loss, VaR, CVaR and the effect of default correlation on the tail.
Credit riskTry itWant to use these apps in your courses? Let’s find out what works for you.
One form, three matters. We answer personally.
We show heyprof on your own material. Tell us what you teach and we will prepare the conversation around it.