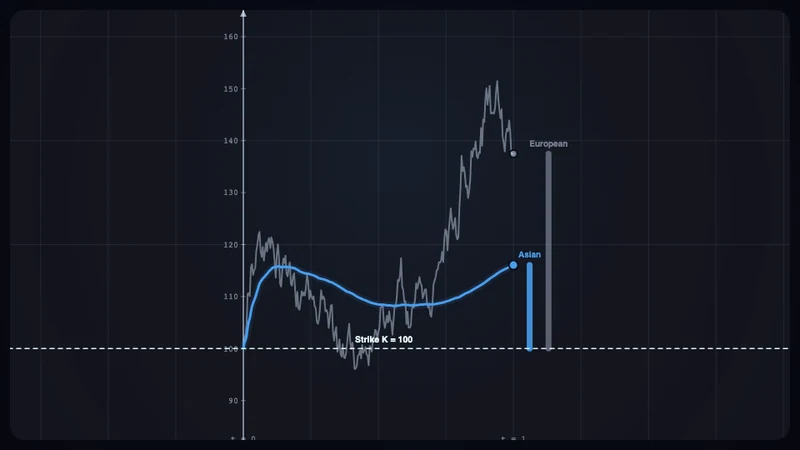
Asian option — details
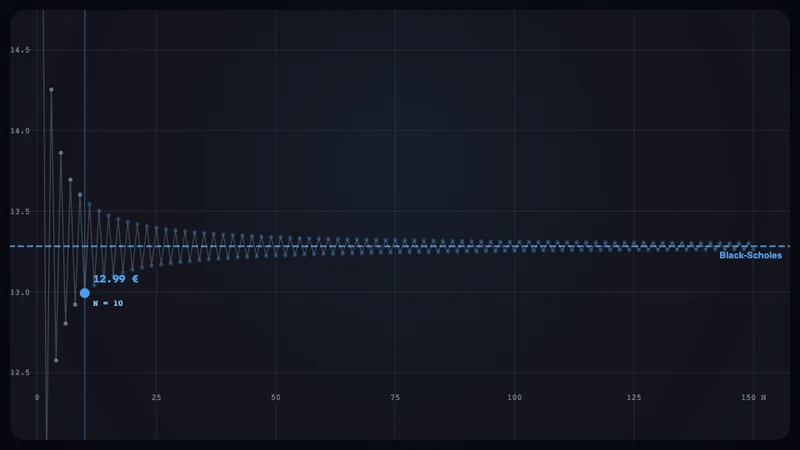
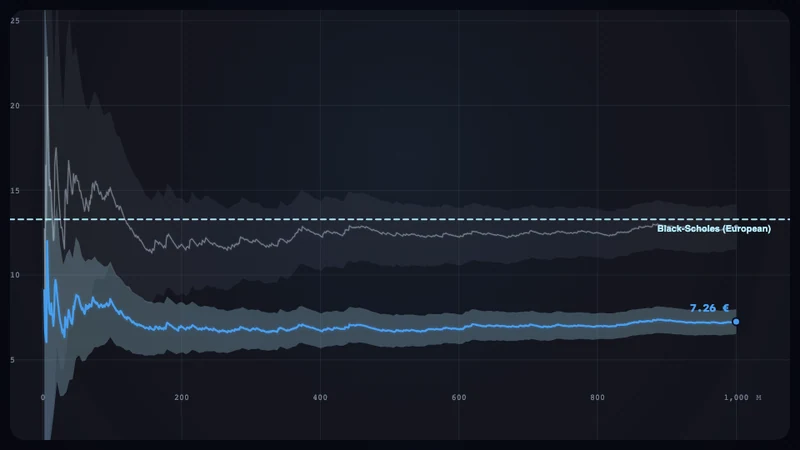
Monte-Carlo pricing with a quantifiable error: the running price estimate with its ±1.96·SE band cinches in at 1/√M; the European estimate from the same paths validates against the analytic Black-Scholes reference. “+1000 paths” animated, “+10000” fast. Debunks “simulation is guessing”.
Financial derivativesTry it